Facebook
 X
 Pinterest
 Copy Link
5 Things to Do Before Purchasing Your First Home
Buying your first home is one of the most exciting – and sometimes overwhelming – milestones in life. Whether you’re looking in Windsor-Essex County, Chatham-Kent or the surrounding areas, being financially and mentally prepared before starting your home search will make the process smoother and less stressful.
As trusted real estate advisors at CENTURY 21 Local Home Team Realty, Inc., we work with many first-time homebuyers, and we know the questions and challenges that come up during the journey. Here are five smart steps to take before purchasing your first home:
1. Pay Off Your Car Loan and Other Debts
When you apply for a mortgage, lenders look at your debt-to-income ratio to decide how much you can afford to borrow. A large monthly car loan or credit card balance can reduce your approval amount—or prevent you from qualifying altogether.
By paying off your car loan and lowering other debts, you’ll:
- Improve your chances of mortgage approval
- Qualify for better interest rates
- Free up cash flow for monthly housing expenses like insurance, utilities, and property taxes
Think of it this way: the less debt you carry, the more financial breathing room you’ll have as a new homeowner.
2. Open a First Home Savings Account (FHSA)
In Canada, first-time buyers have access to an incredible savings tool: the First Home Savings Account (FHSA). This account lets you contribute tax-deductible savings (like an RRSP) while allowing you to withdraw them tax-free when it’s time to buy your first home (like a TFSA).
Key benefits of an FHSA:
- Annual contribution room up to $8,000 (lifetime max $40,000)
- Contributions reduce your taxable income
- Tax-free withdrawals for your first home purchase
Opening an FHSA early gives your money time to grow, helping you build a stronger down payment while taking advantage of tax benefits.
3. Build an Emergency Fund
Owning a home is exciting, but it also comes with unexpected expenses. From leaky roofs to furnace repairs, you’ll want to be financially ready for surprises.
Most financial experts recommend saving three to six months of living expenses in an easily accessible emergency fund. Having this cushion in place protects you from relying on credit cards or loans if something unexpected comes up, ensuring you feel secure in your new home.
4. Check & Improve Your Credit Score
Your credit score plays a big role in your mortgage approval and the interest rate you’ll receive. Before applying for a mortgage:
- Request a copy of your credit report from Equifax or TransUnion
- Dispute any errors you find
- Pay bills on time and keep balances low
- Avoid applying for new credit until after you’ve secured your mortgage
- Even a small improvement in your credit score can mean thousands of dollars in savings over the life of your mortgage.
5. Shop for a 30-Year Mortgage
While many buyers focus on finding the perfect home, securing the right mortgage is just as important. For first-time buyers, a 30-year fixed-rate mortgage often provides stability with lower monthly payments compared to shorter-term options.
Be sure to:
- Compare multiple lenders, not just one
- Ask about first-time homebuyer incentives and programs
- Understand the full cost, including interest rates, closing costs, and penalties
- Taking the time to shop around can help you find the best mortgage product for your financial situation.
Final Thoughts: Your Path to Homeownership…
Purchasing your first home is a big step, but with the right preparation, it doesn’t have to be overwhelming. By paying down debt, using smart savings tools like the FHSA, building an emergency fund, improving your credit score, and carefully shopping for a mortgage, you’ll be in a strong position to move forward with confidence.
At Century 21 Local Home Team Realty, Inc., we believe in guiding our clients every step of the way. Whether you’re just starting to think about buying or you’re ready to view homes in Windsor-Essex County, Chatham-Kent or surrounding areas, we’re here to provide expert advice and trusted local market knowledge.
Ready to start your journey to homeownership? Contact us today to learn how we can help you find your first home.
Len Filiault
Broker of Record
c: 519.890.5045
e: len.filiault@century21.ca
The information provided on this blog is not intended as professional advice and should not be substituted for the guidance of a qualified professional. While we strive to provide accurate and up-to-date information, we make no representations or warranties of any kind, express or implied, about the completeness, accuracy, reliability, suitability, or availability with respect to the blog or the information, products, services, or related graphics contained on the blog for any purpose. Any reliance placed on such information should be independently verified.
Does it Matter What I Wear or Drive?
YES!
First impressions are BIG.
If you pull up to a $3M listing presentation in a 20-year-old Jalopy, it might not go well at the start. But similarly, if you show up in a new Mercedes you can’t afford and are unable to articulate your financial prowess, that could be just as damning.
First impressions do matter, so always keep that in mind because you may not get the opportunity for a second. However, don’t use that as a rationale to buy clothes on credit and finance a car you can’t afford.
Cody Kraus
Broker | Owner
c: 519.322.7105
e: cody.kraus@century21.ca
The information provided on this blog is not intended as professional advice and should not be substituted for the guidance of a qualified professional. While we strive to provide accurate and up-to-date information, we make no representations or warranties of any kind, express or implied, about the completeness, accuracy, reliability, suitability, or availability with respect to the blog or the information, products, services, or related graphics contained on the blog for any purpose. Any reliance placed on such information should be independently verified.
5 Things to Do if You’ve Been Declined for a Mortgage
For many first-time buyers, getting pre-approved for a mortgage is the first big step toward homeownership. But what happens if your mortgage application gets declined?
It can feel discouraging – but it doesn’t mean your dream of owning a home in Windsor or Essex County is over. A decline is often just a temporary setback and an opportunity to strengthen your financial position. Here are five important steps to take if you’ve been declined for a mortgage…
1) Find Out Why You Were Declined
The first thing you should do is ask your lender for the specific reason your application wasn’t approved. Common reasons include:
- A low credit score
- High debt-to-income ratio
- Insufficient down payment
- Employment or income instability
- Errors on your credit report
Understanding why you were declined helps you create a clear plan to address the issue.
2) Review & Improve Your Credit Score
Your credit score is one of the biggest factors in mortgage approval. If your score is too low, take steps to improve it:
- Pay bills on time every month
- Pay down existing credit card balances and loans
- Avoid taking on new debt or applying for multiple credit cards
- Correct any errors on your credit report
Even a small increase in your credit score can make a big difference in your mortgage options and interest rates
3) Reduce Your Debt
Lenders want to see that you can comfortably handle mortgage payments in addition to your other financial obligations. If your debt-to-income ratio is too high, work on paying down outstanding loans or consolidating high-interest debt. For example, paying off a car loan or credit card balance not only improves your financial standing – it can also help increase the amount you may qualify to borrow when you reapply.
4) Build a Bigger Down Payment
Sometimes a mortgage is declined because your down payment isn’t large enough. Consider these options:
- Open a First Home Savings Account (FHSA) to save tax-free for your down payment
- Use your RRSP through the Home Buyers’ Plan
- Set up automatic savings contributions to grow your funds over time
A larger down payment not only improves your chances of approval but can also reduce your monthly mortgage payments.
5) Work with a Mortgage Broker & a Trusted Realtor
If one lender says “no,” that doesn’t mean all will. Mortgage brokers can shop around with multiple lenders, including those that specialize in helping first-time buyers or clients with unique financial situations. At the same time, partnering with a trusted real estate professional – like our team at Century 21 Local Home Team Realty, Inc. – can give you guidance on realistic price ranges, budgeting strategies, and programs available to help first-time buyers.
Being declined for a mortgage is not the end of your homeownership journey – it’s a chance to regroup, strengthen your financial position, and come back better prepared. By improving your credit, lowering debt, saving a stronger down payment, and exploring different lending options, you’ll put yourself in a much stronger position for the future.
At Century 21 Local Home Team Realty, Inc., we’re here to help you every step of the way. If you’ve been declined for a mortgage, let’s connect – we’ll work with you to create a plan so you can move forward with confidence and make your dream of owning a home a reality.
Ready to talk about your options? Contact us today for a no-pressure conversation about how to prepare for your next mortgage application.
Len Filiault
Broker of Record
c: 519.890.5045
e: len.filiault@century21.ca
The information provided on this blog is not intended as professional advice and should not be substituted for the guidance of a qualified professional. While we strive to provide accurate and up-to-date information, we make no representations or warranties of any kind, express or implied, about the completeness, accuracy, reliability, suitability, or availability with respect to the blog or the information, products, services, or related graphics contained on the blog for any purpose. Any reliance placed on such information should be independently verified.
Is a Franchised or Independent Brokerage Better for You?
When it comes to choosing a real estate brokerage, one of the biggest decisions you’ll face is whether to join a franchised brand or an independent brokerage. Both have their merits, but if you’re looking for long-term growth, resources, and the power of a global reputation, a franchised brokerage offers undeniable advantages.
The Power of a Recognized Brand with Local Roots
Trust matters in real estate. Clients want to feel confident that they’re working with a professional who has the backing of a brand they know. A franchised brokerage gives you instant credibility – one that an independent brokerage often takes years to build. Being associated with a name that is recognized and trusted worldwide means clients feel reassured from the very first meeting.
What makes this model even stronger is the combination of global recognition with local ownership and management. While the brand carries weight across the world, the day-to-day operations are run by people who live, work, and invest in the same communities you do. This ensures your clients receive both the strength of a global network and the care of a locally connected brokerage.
Advanced Tech Tools at Your Fingertips
The real estate industry is evolving rapidly, and technology is at the heart of that change. Franchised brokerages invest heavily in cutting-edge platforms, apps, and marketing systems that help agents work smarter, not harder. From digital listing presentations to AI-driven marketing tools, you’re equipped to deliver a seamless experience that today’s buyers and sellers expect.
Strong Industry Partnerships
Franchised brands have the advantage of scale. With established industry partnerships – whether with mortgage lenders, home service providers, or marketing platforms – agents gain access to resources and opportunities that independents simply can’t match. These partnerships translate into better value and more options for your clients, strengthening your ability to provide a full-service experience.
A Global Network of Agent Referrals
One of the most powerful advantages of a franchised brokerage is the network. With thousands of agents worldwide, you’re never limited to your local market. Need to connect a relocating client with a trusted agent across the country – or across the globe? A franchise gives you direct access to a referral system that keeps business flowing, no matter where your clients are headed.
The Best of Both Worlds
At a franchised brokerage, you enjoy the personal connections and community focus that define real estate, but with the added benefits of a powerful global brand, modern technology, and proven support systems. For many agents, it’s not just about having more tools – it’s about having the right tools, local leadership, and global reach to build a sustainable, successful career.
In the end, while independent brokerages may offer flexibility, the unmatched resources, reputation, and reach of a franchised brokerage – combined with local ownership and management – can make all the difference in helping you thrive in an increasingly competitive industry.
Ready to Take the Next Step?
If you’re an agent considering your next move, or a client looking for trusted real estate guidance, Century 21 Local Home Team Realty Inc. is here for you. Backed by one of the most recognized names in real estate and proudly owned and operated right here in our community, we’re committed to helping you achieve your goals.
Learn how we can support YOUR real estate journey…
Len Filiault
Broker of Record
c: 519.890.5045
e: len.filiault@century21.ca
The information provided on this blog is not intended as professional advice and should not be substituted for the guidance of a qualified professional. While we strive to provide accurate and up-to-date information, we make no representations or warranties of any kind, express or implied, about the completeness, accuracy, reliability, suitability, or availability with respect to the blog or the information, products, services, or related graphics contained on the blog for any purpose. Any reliance placed on such information should be independently verified.
Retiring to Windsor-Essex County: The Best Decision You Could Make
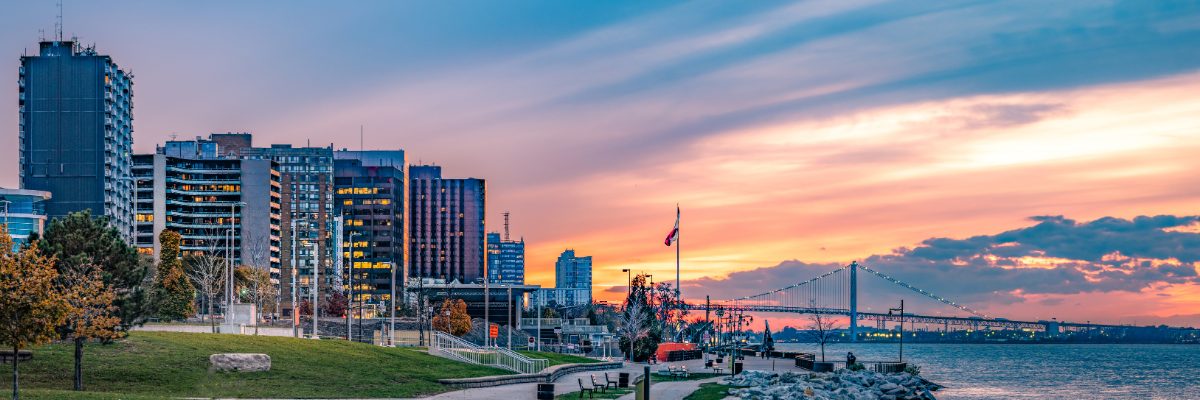
When it comes to choosing the perfect place to retire, Windsor-Essex County truly checks all the boxes. Nestled in the southernmost part of Canada, our region offers a blend of affordability, convenience, and lifestyle that’s hard to beat!
Whether you’re looking for a slower pace, a thriving community, or easy access to travel, Windsor-Essex may be the retirement destination you’ve been searching for.
Here are the Top 8 Reasons why retiring in Windsor-Essex County could be the best decision you ever make…
1. The Warmest Climate in Canada
Windsor-Essex boasts the mildest climate in the country. With longer summers, shorter winters, and plenty of sunshine, you’ll spend more time outdoors enjoying what retirement is meant to be: relaxation, activity, and fresh air.
2. Affordable Housing & a Condo Boom
Compared to many Canadian cities, housing here is significantly more affordable. Retirees often find they can downsize and still free up equity. On top of that, the region has a surplus of modern condominiums, perfect for low-maintenance living, so you can focus on enjoying your retirement, not maintaining a home.
3. Proximity to Detroit & Easy Travel Options
Love to travel? Windsor’s location is unbeatable. We’re just minutes from Detroit Metropolitan Airport, offering direct flights to Florida, Europe, and beyond. Plus, VIA Rail stations make train travel across Ontario quick and stress-free.
4. A Quicker Drive to Florida
If you prefer to head south by car, Windsor gives you a head start. Being in the southernmost part of Canada means your drive to Florida is several hours shorter compared to retirees in other provinces. That’s more sunshine, less highway.
5. Vibrant Arts, Culture & Dining
Retirement isn’t just about slowing down – it’s about living well. Windsor-Essex offers a thriving cultural scene, from art galleries and wineries to world-class dining. You’ll always find something to enjoy close to home.
6. Active Living for Every Interest
For those who love to stay active, Windsor-Essex has no shortage of options. From scenic golf courses and thriving pickleball clubs to modern ice rinks for skating and hockey, you’ll find plenty of ways to keep moving, stay social, and enjoy a healthy retirement lifestyle.
7. Strong Healthcare & Community Services
Our region is home to modern healthcare facilities and growing services geared toward retirees, ensuring peace of mind as you transition into your next chapter.
8. A Welcoming Community
Perhaps the biggest reason to retire in Windsor-Essex: the people. This is a region built on strong communities, welcoming neighbours, and a warm, small-town feel – paired with the conveniences of a larger city.
Retirement is about lifestyle, and Windsor-Essex County delivers. With affordable housing, the best climate in Canada, endless activities, easy access to travel, and a welcoming community, it’s no wonder more and more retirees are calling this region home.
If you’re thinking about making a move, the team at CENTURY 21 Local Home Team Realty Inc. is here to guide you every step of the way…
Len Filiault
Broker of Record
c: 519.890.5045
e: len.filiault@century21.ca